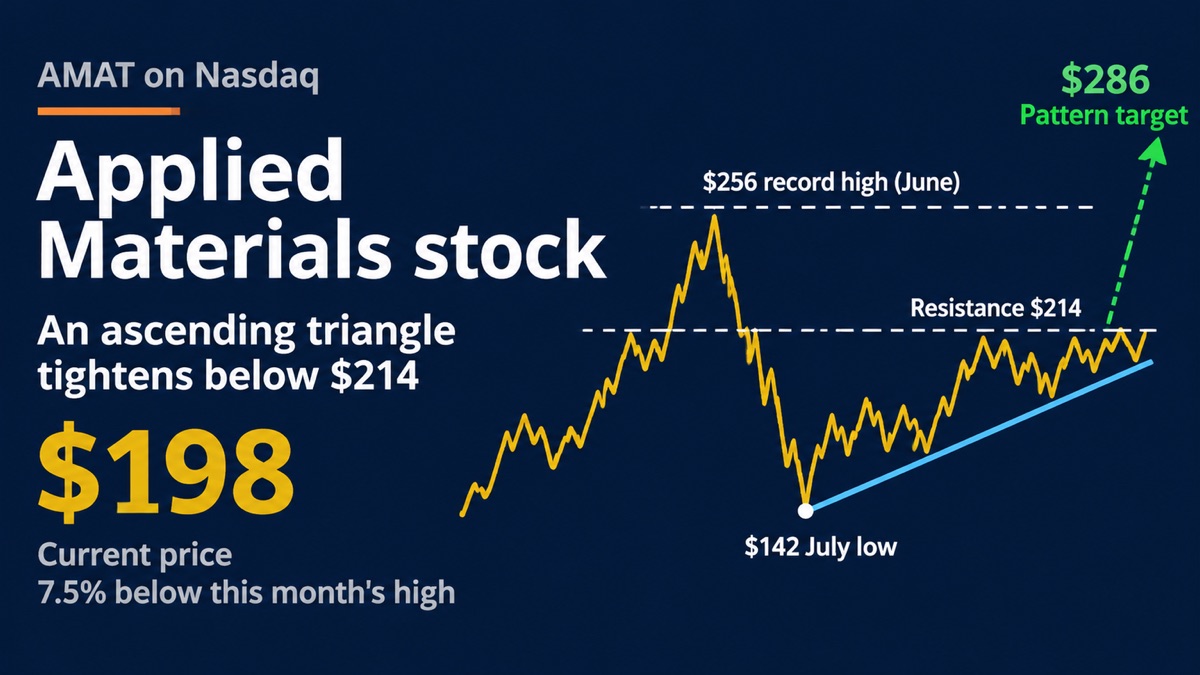
Applied Materials stock has spent the past several weeks stuck in a narrowing range, trading near $198 after failing to clear this month’s high of $214. The pause follows a climb off the summer low, with the next tool-order report sitting just ahead of the range.
Shares sit about 7.5% below that monthly high but roughly 39% above the July low of $142, after a fall from June’s record of $256. The drop from the record to the low was about 45%. The recovery since then has been a grind of higher lows, not a spike.
The range now waits on the next report, where revenue is projected to rise about 22% from a year earlier, and on whether $214 gives way.
Where the shares stand now
Applied Materials trades on Nasdaq under the ticker AMAT. The orders that matter are wafer-fab tools, the deposition and related systems chip plants buy when they add capacity. The table uses $198 as the measuring point.
| Level | Price | Distance from $198 |
|---|---|---|
| All-time high (June) | $256 | +29.3% |
| Recent resistance (this month’s high) | $214 | +8.1% |
| Current price | $198 | n/a |
| July low | $142 | -28.3% |
The ascending triangle setup
Higher lows since July, a ceiling near $214. That is the ascending triangle. The floor keeps rising. The offer at the top has not.
From $142 to $214 is $72. Added to the ceiling, the measured target is about $286. A trade through $256, the June record, would say the pattern resolved up rather than failing at the same line again.
Why chart patterns are not guarantees
If the rising trendline breaks, $142 is the known low and $286 drops out of the working case. Nothing in the drawing requires the next buyer to show up.
The business case behind the rally
Foundries and memory makers have kept tool budgets open for capacity they already announced. That is a slower story than a single product cycle, and it fits a stock that has climbed without breaking out. The next report is expected to show revenue up about 22% from a year earlier.
A 22% print with a softer order guide leaves the shares under $214. A 22% print with orders that still cover the next few quarters gives that line less support.
What analysts expect next
The estimate is about 22% revenue growth, with systems revenue doing the work. Margin is expected to stay steady if the tool mix does not shift toward lower-priced service. Revenue versus that 22% is the figure the range is leaning on.
Orders that keep the book visible
These tools are booked ahead of shipment. A pushout shows up in the guide before it shows up in a single week of trading. That lead time is why the stock has been able to hold higher lows while it waits.
Valuation and the levels that matter
At $198, Applied Materials is about 23% under the June record of $256. It is no longer at the summer low, and it is not through the month’s high. The open question sits between $142 and $214.
Above $214, the record is back in range and the triangle math points toward $286. Under the rising line, the climb from July is the thing that failed.