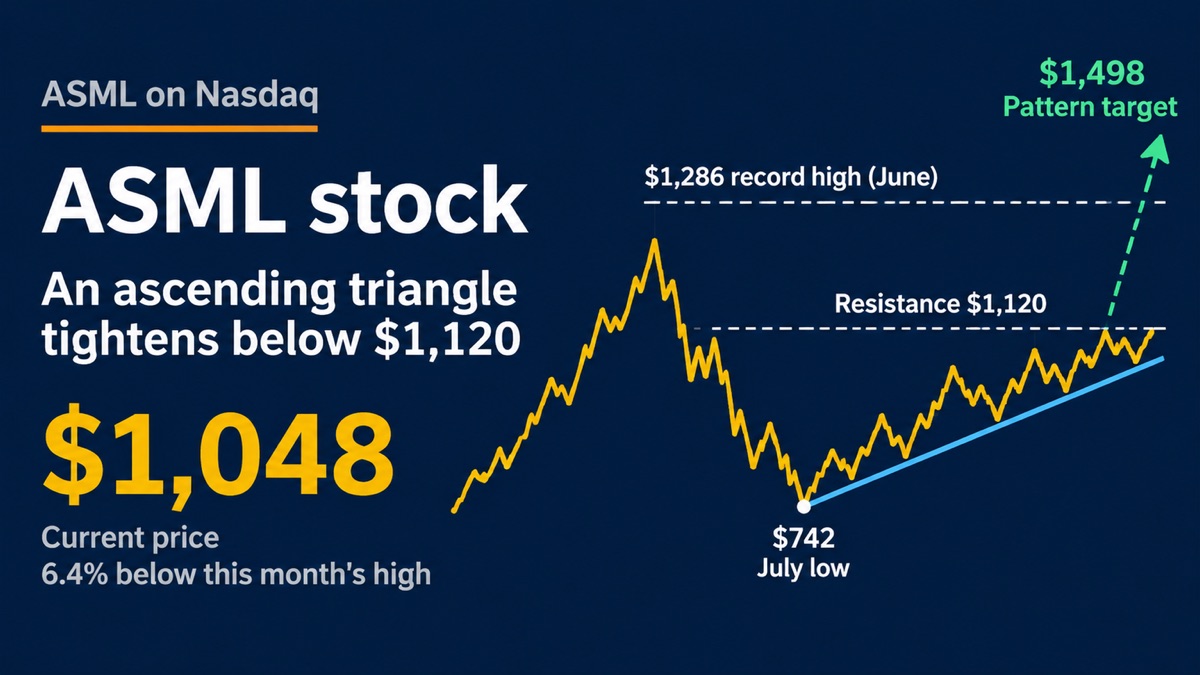
ASML stock has spent the past several weeks stuck in a narrowing range, trading near $1,048 after failing to clear this month’s high of $1,120. The pause comes after a climb off the summer low, and it now sets up a clear test: whether buyers can push the shares through a ceiling they have already met.
Shares sit about 6.4% below that monthly high but roughly 41% above the July low of $742, a level reached after a fall from June’s record of $1,286. That round trip, a drop of about 42% followed by a series of higher lows, is why the band is being watched so closely.
What happens next likely depends on two things: the company’s upcoming report, where revenue is projected to rise about 24% from a year earlier, and whether the chart pattern formed in the consolidation resolves upward or breaks down.
Where the shares stand now
ASML trades on Nasdaq under the ticker ASML. The business under the chart is extreme-ultraviolet lithography tools, the machines advanced chip plants still have to order. The table below shows the key price levels in this read, measured from $1,048.
| Level | Price | Distance from $1,048 |
|---|---|---|
| All-time high (June) | $1,286 | +22.7% |
| Recent resistance (this month’s high) | $1,120 | +6.9% |
| Current price | $1,048 | n/a |
| July low | $742 | -29.2% |
The ascending triangle setup
Since the July bottom, the stock has made higher lows while stalling near $1,120. Readers of charts call that an ascending triangle: a flat ceiling and a rising floor. Buyers have paid up from the low. Sellers have held the same line.
A common target takes the height of the pattern and adds it to resistance. The distance from $742 to $1,120 is $378, which points to about $1,498. A move through the $1,286 record would show the range has given way, rather than another stop at the same shelf.
Why chart patterns are not guarantees
The drawing can fail. If the rising line breaks, $742 is a price the market has already traded, and $1,498 stops being the working target. A pattern records where orders clustered. It does not force the next order.
The business case behind the rally
Chip plants have kept placing tool orders even as some memory and logic projects slip a quarter. That backlog is the fundamental story under the chart. The next report is expected to show revenue up about 24% from the year-ago quarter, a step tied to tool shipments rather than a new product line.
The risk is a pause in those bookings. A 24% revenue print with a thinner order book would leave the stock inside the range. A 24% print with bookings that still cover the following quarters would give $1,120 a reason to break.
What analysts expect next
The working estimate is revenue growth of about 24% year over year, led by lithography systems. Gross margin is expected to hold if the mix stays weighted to the newer tools. The first figure that moves this range is revenue against that bar. The second is whether management still talks about a full shipment schedule.
Orders that keep the book visible
Leading chip makers book these tools months ahead. That does not lock the share price, and a customer can still slide a delivery. It does make the next quarter less of a coin flip than a pure spot business. The higher lows on the chart line up with that visibility.
Valuation and the levels that matter
At $1,048, ASML is still about 19% under the June record of $1,286. The shares have recovered the summer low and have not been allowed to price in a clean break of the tool cycle. The band between $742 and $1,120 is the wait.
A close above $1,120 would put the old high back in range and, on the triangle math, open a path toward $1,498. A close under the rising trendline would say the recovery has stalled. Until one of those prints arrives, the stock stays tight, just under the line it has not crossed.